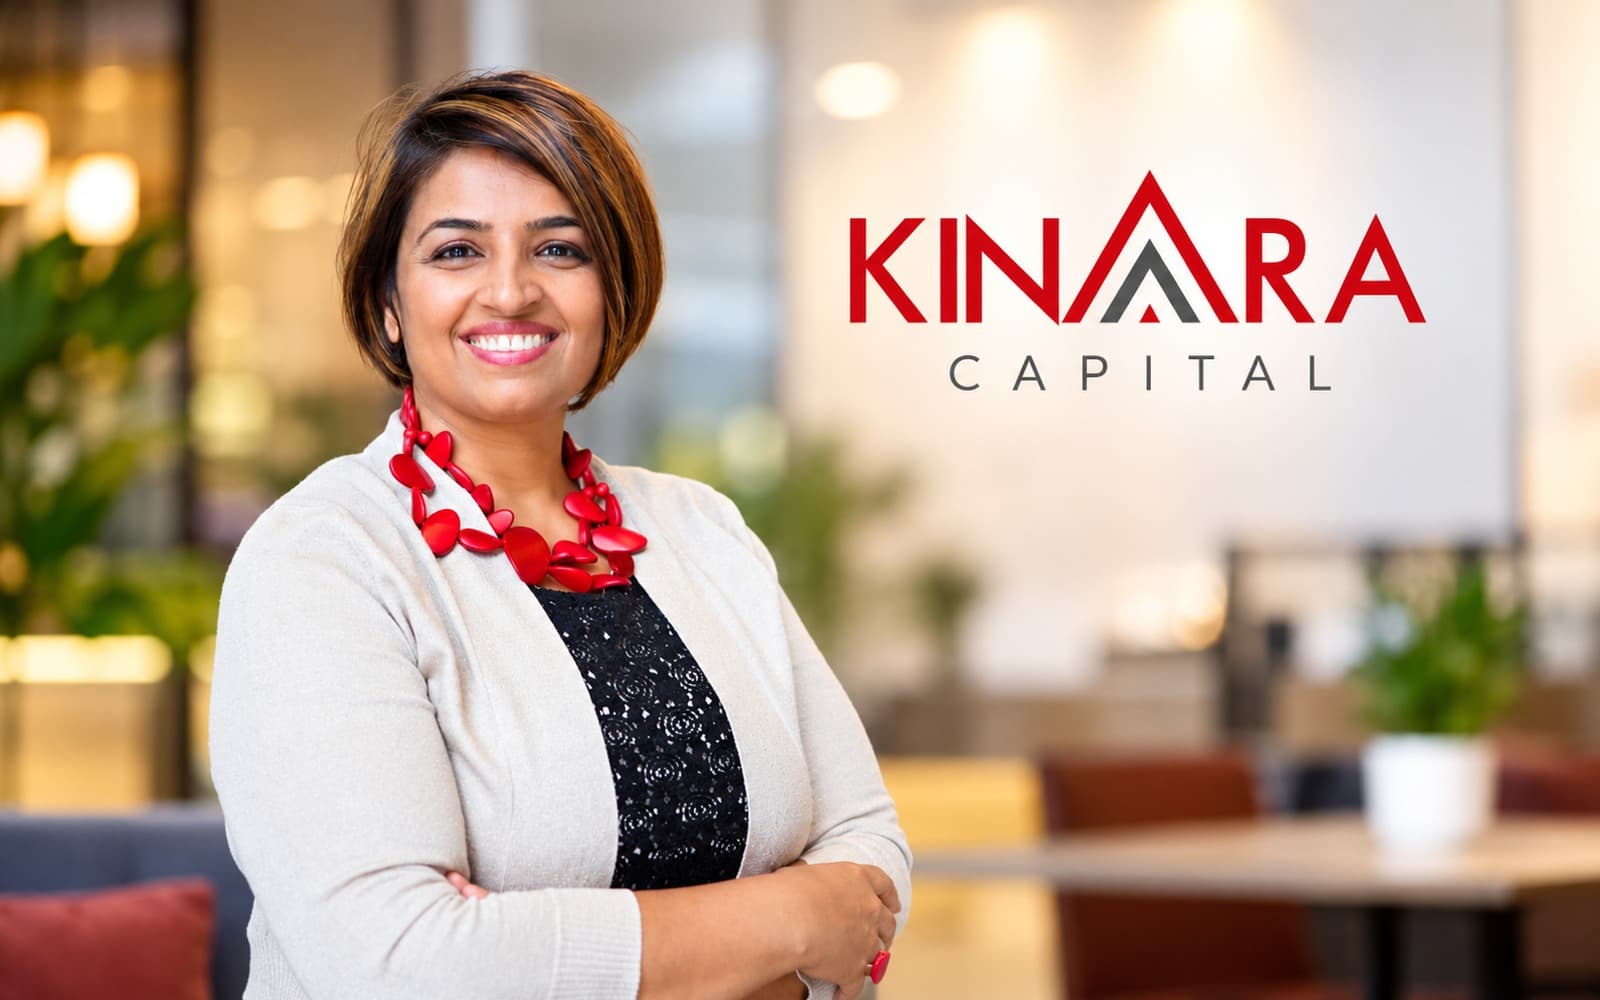
Hardika Shah: Building Kinara Capital and Making Business Loans More Accessible to India's Small Businesses
Discover how Hardika Shah moved from an international consulting career to founding Kinara Capital, a fintech company focused on improving access to business credit for India's micro, small and medium enterprises. Explore her entrepreneurial journey, the challenges of responsible lending, the role of technology in financial inclusion, and the importance of supporting women entrepreneurs.
In this story10 sections
- 1.1. A Journey Driven by Financial Inclusion and Entrepreneurial Purpose
- 2.2. From International Consulting to Understanding India's Business Challenges
- 3.3. Recognising the Credit Gap for Small Businesses
- 4.4. Founding Kinara Capital in 2011
- 5.5. Combining Technology with a Practical Lending Model
- 6.6. Building a Sustainable Business While Expanding Access to Credit
- 7.7. Supporting Women Entrepreneurs Through HerVikas
- 8.8. Expanding Beyond Individual Loans to Local Economic Impact
- 9.9. Lessons Entrepreneurs Can Learn from Hardika Shah
- 10.10. Hardika Shah's Continuing Mission to Make Business Finance More Accessible
Category: Finance, Fintech & Entrepreneurship
Founder: Hardika Shah
Company: Kinara Capital
Location: Bengaluru, India
Reading time: 8 min read
1. A Journey Driven by Financial Inclusion and Entrepreneurial Purpose
For many small businesses, growth depends on having access to the right amount of capital at the right time. A manufacturer may need new machinery to fulfil a larger order. A retailer may require additional inventory before a busy season. A small workshop may need working capital to manage payments to suppliers and employees.
Yet obtaining formal business credit has historically been difficult for many micro and small enterprises, particularly those without substantial property assets to offer as security.
Hardika Shah built her entrepreneurial mission around this challenge. After spending nearly two decades in management consulting, she founded Kinara Capital in 2011 with the aim of making formal business financing more accessible to underserved small-business entrepreneurs in India.
Her journey reflects a broader change in financial services: the recognition that small businesses need lending solutions designed around their operating realities, rather than financial products that work only for companies with established banking relationships and significant assets.
Kinara Capital's approach combines technology-enabled credit assessment with customer service and a focus on the financing needs of micro, small and medium enterprises (MSMEs).
For Shah, the objective was not simply to build another lending company. It was to develop a business capable of addressing a persistent gap in India's financial system while operating on a sustainable commercial foundation.
2. From International Consulting to Understanding India's Business Challenges
Before becoming a fintech entrepreneur, Hardika Shah built her career in management consulting. She spent nearly two decades working on complex projects for international businesses across the United States, Europe and the Asia-Pacific region.
Her professional experience included work involving business strategy, technology, operations and organisational performance. These responsibilities provided exposure to how companies make decisions, manage resources and build systems that can operate at scale.
Shah also pursued higher education in the United States. She earned a bachelor's degree in computer science from Knox College and later completed an MBA through a joint programme involving Columbia Business School and the University of California, Berkeley's Haas School of Business.
Her consulting career provided a foundation in analytical thinking and business management. However, her interest in entrepreneurship developed from a problem closer to home.
Shah grew up watching her mother operate a small shop in Mumbai's Mulund neighbourhood. Through that experience, she became aware of the practical difficulties faced by small-business owners, particularly when they needed financing to develop their businesses.
The experience offered an important perspective on the difference between understanding business through corporate projects and experiencing the day-to-day financial pressures of running a small enterprise.
A business can have customers, a viable product and opportunities for growth, yet still struggle to expand when it cannot secure the working capital it needs.
That gap between entrepreneurial potential and access to finance became central to Shah's eventual decision to build a business of her own.
3. Recognising the Credit Gap for Small Businesses
Small enterprises play an important role in India's economy. They manufacture products, operate shops, provide services, employ workers and support supply chains across numerous industries.
However, their financing requirements do not always fit neatly into traditional lending models.
A small manufacturer may have regular orders and reliable customers but limited property ownership. A trading business may generate steady revenue while experiencing seasonal cash-flow fluctuations. A growing workshop may need funds to purchase equipment before the additional production generates income.
For such businesses, the absence of acceptable collateral or a long-established formal credit history can make borrowing difficult.
Shah recognised an opportunity to develop a lending model that considered more than the property assets a business owner could pledge.
The challenge was substantial. A lender serving small enterprises must understand different industries, assess repayment capacity, manage operating costs and maintain disciplined credit decisions. Expanding access to finance cannot come at the expense of responsible underwriting.
The business therefore needed to balance two objectives: make credit more accessible to underserved entrepreneurs and manage the financial risks involved in lending to them.
This was the problem Kinara Capital set out to address.
Rather than concentrating exclusively on larger companies or borrowers with extensive assets, the business focused on micro and small enterprises that needed financing to operate, invest and grow.
The opportunity was not simply to distribute more loans. It was to create a more practical route for eligible small businesses to obtain formal credit.
4. Founding Kinara Capital in 2011
In 2011, Shah left her established consulting career and returned to India to launch Kinara Capital.
The move represented a significant professional transition. Consulting had given her experience working with large organisations, but building a financial services company required a different set of capabilities.
A lending business must develop reliable systems for assessing borrowers, making credit decisions, disbursing funds, collecting repayments and managing its cost of capital. It must also earn the confidence of customers, employees, investors and funding partners.
Kinara Capital began on a modest scale, initially operating from a home office with a small team. Shah and her colleagues had to establish the business while developing the processes required to serve a market with diverse financing needs.
The early years brought difficult questions.
How could the company assess businesses that lacked conventional forms of collateral? How could it reach entrepreneurs beyond established banking networks? How could it keep operating expenses under control while maintaining appropriate credit standards?
These questions were central to the company's development.
Shah's strategy focused on building lending processes around the needs of small enterprises while using technology and structured credit assessment to support decision-making.
The company gradually developed its presence in industrial and commercial markets, serving businesses involved in manufacturing, trading and related services.
Its progress demonstrated the potential for a specialised financial institution to focus on borrowers who were often overlooked by conventional lending models.
However, growth in lending also required discipline. Every loan created an obligation for the borrower and a financial exposure for the lender. Sustainable expansion depended on evaluating these risks carefully rather than pursuing volume alone.
5. Combining Technology with a Practical Lending Model
Technology became an important part of Kinara Capital's approach to improving access to business finance.
Traditional lending processes can involve extensive documentation, repeated visits and long decision-making cycles. For a small-business owner managing production, employees and customers, these requirements can make obtaining credit particularly difficult.
Kinara developed digital systems to support loan origination, management and credit assessment. Its approach combines data-driven decision-making with customer-facing assistance rather than relying entirely on automated interactions.
The company's current offering includes the multilingual myKinara application, which allows prospective borrowers to check eligibility and access the loan process digitally.
Kinara also describes its credit assessment approach as incorporating artificial intelligence and machine learning. These tools can help organise information and support lending decisions, although the quality of those decisions ultimately depends on appropriate data, risk controls and sound lending practices.
The company has also maintained an emphasis on customer service, including assistance for entrepreneurs who may prefer to communicate in regional languages or need help understanding the application process.
This combination of digital tools and direct support addresses an important practical consideration: financial technology is useful only when customers can access and understand it.
For a small manufacturer or retailer, a more convenient application process can reduce administrative friction and make formal financing easier to explore.
The larger lesson is that technology should solve a specific customer problem. In Kinara's case, that problem involves making the assessment and delivery of small-business credit more accessible while maintaining responsible lending standards.
6. Building a Sustainable Business While Expanding Access to Credit
Making loans available to underserved businesses is only one part of building a successful lending company. The other is ensuring that the business can manage risk and remain financially sustainable.
Kinara's early journey illustrates this challenge.
According to reporting by Inc42, the company spent its first several years working towards profitability. In a lending business, interest income must cover funding costs, operating expenses, credit losses and other obligations. A company can expand its customer base and still struggle if those underlying economics are not managed carefully.
For Kinara, responsible growth required systems capable of evaluating borrowers consistently and monitoring repayment performance.
It also required understanding the different cash-flow patterns of small businesses. A manufacturer, a retailer and a service provider may have very different financing requirements and repayment capacities.
The ability to offer credit without requiring conventional property collateral does not mean that lending decisions can ignore risk. Lenders still need to assess the borrower's business, income, obligations and capacity to repay.
This distinction is important when evaluating financial inclusion initiatives. Increasing access to credit is valuable when financing supports viable business activity and borrowers understand their repayment commitments.
Shah's journey highlights the need to align social purpose with commercial discipline.
A sustainable financial institution can continue serving entrepreneurs over time only if its lending model, customer relationships and operating processes remain viable.
The broader principle applies to many purpose-driven businesses: solving a social problem and building a sustainable company must reinforce one another.
7. Supporting Women Entrepreneurs Through HerVikas
Women's participation in entrepreneurship is another important part of Kinara Capital's work.
Women who operate micro and small businesses can encounter additional obstacles when seeking formal finance, including limited access to assets, documentation challenges and gaps in established banking relationships.
To address this issue, Kinara introduced HerVikas, a programme focused on supporting women-owned micro, small and medium enterprises through access to business financing.
The programme forms part of the company's wider emphasis on financial inclusion and gender parity.
Kinara has also highlighted its women-majority management team as an element of its organisational culture. This reflects an effort to incorporate inclusion into the company's internal structure as well as its customer-facing mission.
The significance of initiatives such as HerVikas extends beyond providing capital. Access to appropriate financing can help eligible entrepreneurs invest in equipment, manage working capital, increase production or pursue new business opportunities.
However, financing alone does not guarantee business success. Outcomes depend on market demand, business management, repayment obligations and wider economic conditions.
For women entrepreneurs, the availability of formal credit can nevertheless be an important part of building a more resilient business.
HerVikas illustrates how a specialised financial institution can develop programmes around the needs of a particular customer group while remaining connected to its core lending business.
It also reinforces an important point about financial inclusion: expanding access means understanding the circumstances of customers who have historically found formal financial services harder to obtain.
8. Expanding Beyond Individual Loans to Local Economic Impact
A small-business loan can affect more than the business owner who receives it.
Financing used to purchase machinery may help a manufacturer increase production. Working capital may allow a trader to maintain inventory and fulfil orders. Investment in business equipment may improve operating capacity and create opportunities for additional employment.
These outcomes are not automatic, but they illustrate why small-business finance can have effects beyond an individual transaction.
Kinara Capital's focus on manufacturing and trading enterprises places it within this broader economic context.
The company reports operating across more than 100 cities and supporting businesses in hundreds of subsectors. Its geographical reach reflects an emphasis on serving commercial and industrial markets beyond a narrow group of major corporate borrowers.
Local businesses frequently operate close to the communities they serve. Their activity supports suppliers, workers, transport providers and other participants in regional economies.
When a viable enterprise gains access to suitable financing, it may be better positioned to purchase equipment, fulfil orders or manage fluctuations in cash flow.
At the same time, responsible lending remains essential. Borrowing introduces repayment obligations, and financing that is unsuitable for a business can create additional pressure rather than solve its problems.
For this reason, the long-term contribution of a lending business should be assessed not only by the amount of money disbursed but also by the quality of its lending, the sustainability of its operations and the needs of the customers it serves.
Shah's work reflects an approach to fintech that places small enterprises at the centre of the financial services model.
9. Lessons Entrepreneurs Can Learn from Hardika Shah
Hardika Shah's journey offers several lessons for founders building businesses in financial services and other industries.
1. Start with a clearly defined problem.
Kinara Capital emerged from a specific challenge: viable small businesses often struggled to obtain formal credit on suitable terms. A clear understanding of the problem helped shape the company's purpose and target market.
2. Use professional experience as a foundation, not a limitation.
Shah's consulting background gave her experience in business strategy, technology and operations. She applied that experience to a different environment, demonstrating how professional skills can transfer into entrepreneurship.
3. Understand the realities of your customers.
Small-business owners have practical needs involving cash flow, inventory, equipment and repayment schedules. Businesses are more useful when their products reflect the circumstances of the people using them.
4. Combine technology with human understanding.
Digital systems can improve efficiency, but customers may still need explanations, assistance and local-language support. The right balance depends on the market and the complexity of the service.
5. Treat risk management as part of the business model.
In financial services, growth must be supported by sound credit assessment, cost control and appropriate repayment structures. Expanding access without managing risk can undermine both the company and its customers.
6. Build inclusion into the operating model.
Initiatives such as HerVikas show how a company can focus on customers who face specific barriers to accessing formal financial services. Inclusion becomes more meaningful when it is reflected in products, processes and organisational priorities.
7. Measure success over the long term.
Building a lending business takes time. Sustainable growth depends on customer relationships, operational discipline and a business model capable of withstanding difficult periods, not simply on rapid expansion.
10. Hardika Shah's Continuing Mission to Make Business Finance More Accessible
Hardika Shah's transition from international consulting to fintech entrepreneurship illustrates how identifying an underserved market can become the starting point for a substantial business opportunity.
Through Kinara Capital, she has focused on improving access to formal credit for India's micro and small enterprises, combining technology-enabled lending processes with customer service and a commitment to financial inclusion.
The journey has involved more than developing a digital platform. It has required building lending operations, managing credit risk, developing customer relationships and working towards a sustainable financial model.
Her focus on women-owned businesses through HerVikas also demonstrates how a company's mission can influence the groups it seeks to serve.
For aspiring entrepreneurs, the central lesson is straightforward: a business can create meaningful value when it addresses a genuine problem and builds the systems needed to solve it consistently.
Small businesses need more than ambition to grow. They need customers, capable teams, reliable operations and access to appropriate financial resources. When financing is structured responsibly, it can help viable enterprises pursue opportunities that might otherwise remain out of reach.
Shah's story is therefore part of a larger conversation about the role of fintech in India's economic development. The next phase of financial inclusion will depend on making services more accessible while ensuring that customers, lenders and local economies can benefit from sustainable growth.
Her entrepreneurial journey offers a useful example of how a clear purpose, professional experience and long-term execution can come together to address a persistent business challenge.
More Finance stories
Gajendra Kothari: From a Middle-Class Background to Building Etica Wealth and Championing Financial Freedom
Discover how Gajendra Kothari transitioned from a career at UTI Mutual Fund to co-founding Etica Wealth Management. Explore his entrepreneurial journey, commitment to ethical financial advice, investor education, and the importance of disciplined, long-term investing.
Read story
Building a Financial Distribution Business: How Shifali Satsangee Founded Funds Ve'daa
Discover how Shifali Satsangee helped build Funds Ve'daa into a mutual fund distribution business through investor education, trusted relationships, financial expertise, and a commitment to helping people make informed investment decisions.
Read story
From Newspaper Clippings to a Trusted Investment Research Business: The Story of Dhirendra Kumar
Discover how Dhirendra Kumar built Value Research into a trusted Indian investment research business, helping investors understand mutual funds, compare investment options, and make informed financial decisions.
Read story