Building a Financial Distribution Business: How Shifali Satsangee Founded Funds Ve'daa
Discover how Shifali Satsangee helped build Funds Ve'daa into a mutual fund distribution business through investor education, trusted relationships, financial expertise, and a commitment to helping people make informed investment decisions.
In this story20 sections
- 1.The Story
- 2.1. Recognising an Opportunity in a Traditional Investment Market
- 3.2. Building the Business on Existing Relationships
- 4.3. Shifali Satsangee's Journey Into Financial Services
- 5.4. Building Credibility in a Relationship-Driven Industry
- 6.5. Creating a Distinctive Business Model
- 7.6. Taking Financial Education Beyond the Office
- 8.7. Expanding Beyond High-Net-Worth Investors
- 9.8. Building Processes for Consistent Client Service
- 10.9. Embracing Technology and Professional Development
- 11.10. Learning to Build a Business That Does Not Depend on One Person
- 12.11. What Other Entrepreneurs Can Learn From Shifali Satsangee
- Start With a Real Market Need
- Use Existing Relationships as a Starting Point
- Build Credibility Through Expertise
- Educate Customers Instead of Simply Selling to Them
- Develop Processes Before Growth Becomes Difficult
- Adapt to Changing Customer Expectations
- Think in Terms of Long-Term Relationships
- 13.The Bigger Picture
Building a Financial Distribution Business: How Shifali Satsangee Founded Funds Ve'daa
Discover how Shifali Satsangee helped build Funds Ve'daa into a recognised mutual fund distribution business in Agra, bringing professional investment services to investors in a market traditionally dominated by gold, fixed deposits and other familiar savings options.
Category: Finance & Entrepreneurship
Founder: Shifali Satsangee
Company: Funds Ve'daa
Location: Agra, Uttar Pradesh, India
Reading Time: 9 min
The Story
Some businesses are built around products people already understand. Others grow by helping people discover possibilities they have never seriously considered.
For Shifali Satsangee, the opportunity lay in a part of India's financial services industry that was still developing in smaller cities: mutual fund distribution.
In Agra, where gold, fixed deposits and property had long played important roles in household financial decisions, professional investment services were not as widely established as they were in larger financial centres. Many investors needed more than access to investment products. They needed someone who could explain their options, understand their financial circumstances and help them make informed decisions.
Shifali saw an opportunity to build a business around that need.
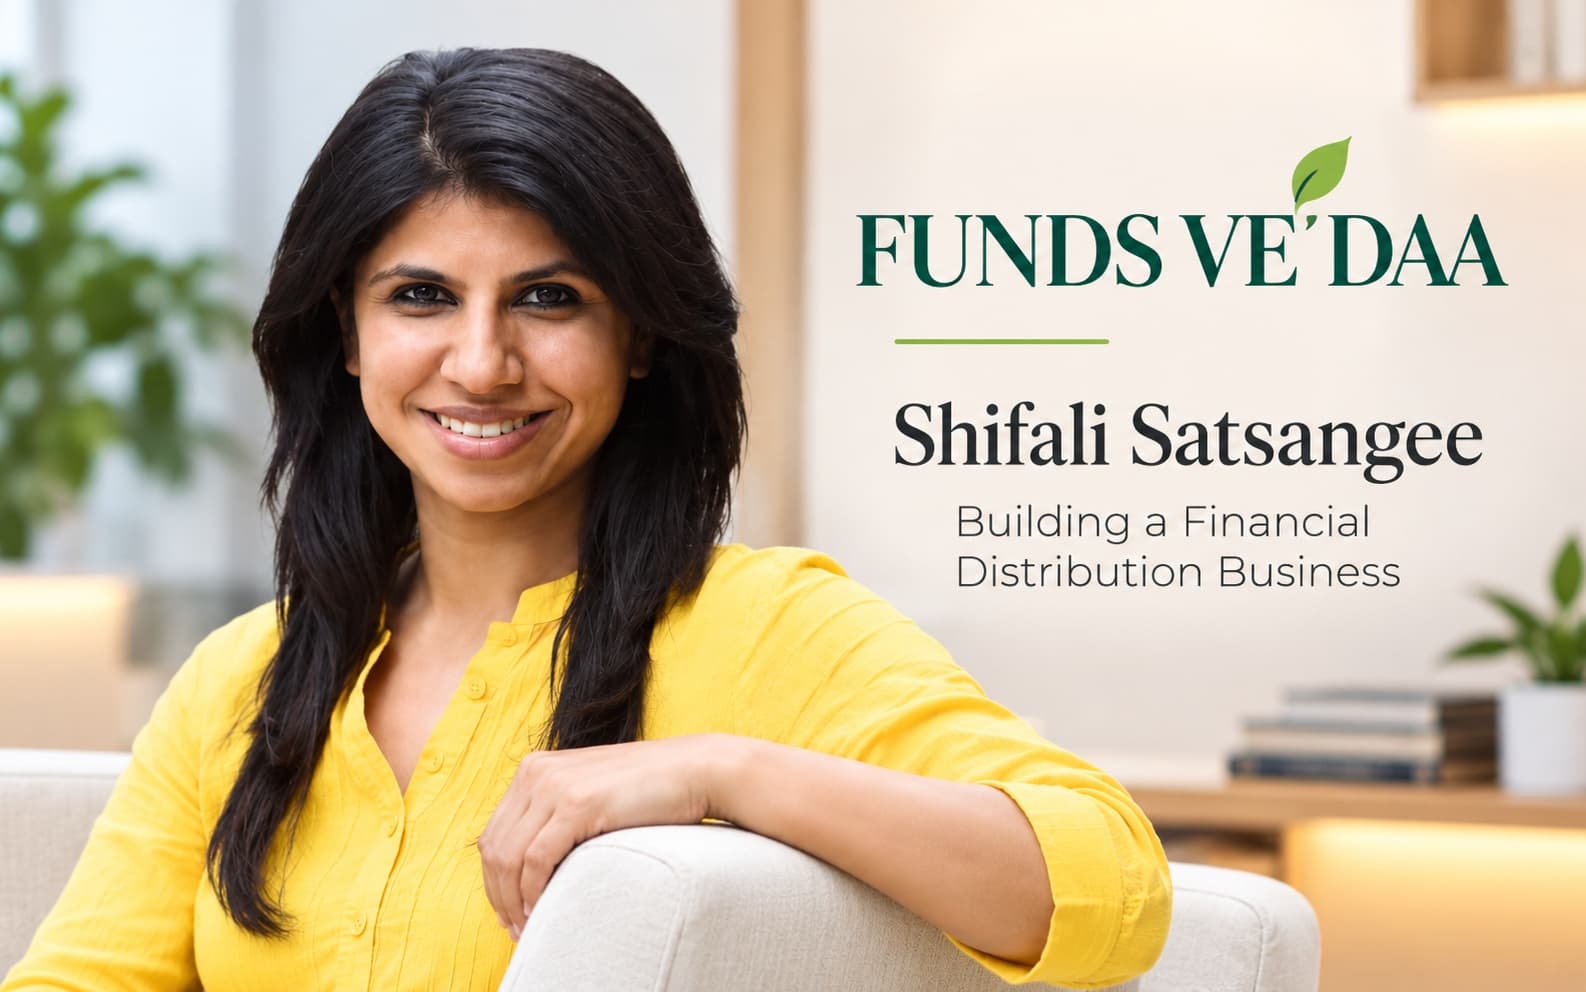
Working alongside her husband, chartered accountant Sahib P. Satsangee, she helped develop Funds Ve'daa, a mutual fund distribution business that began its journey in 2002. Over time, the firm developed its approach around investor relationships, research, financial education and disciplined business processes.
Her journey illustrates an important aspect of entrepreneurship: building a sustainable financial services business requires more than understanding markets. It requires earning trust, educating customers and creating systems that can support relationships over many years.
1. Recognising an Opportunity in a Traditional Investment Market
The origins of Funds Ve'daa can be traced to 2002, when Shifali and her husband began exploring opportunities to expand into mutual fund distribution.
Sahib had been providing accounting and legal services through his professional practice. While considering diversification, the couple recognised a gap in the local financial services market. Professional expertise in investment distribution and portfolio-related services was relatively limited in and around Agra.
The opportunity was not simply to introduce another financial product. It was to help investors understand an additional way of allocating their savings.
Gold, fixed deposits and property were familiar choices for many households. Mutual funds, by comparison, required a different understanding of market-linked investments, risk and the relationship between investment decisions and long-term financial goals.
The founders believed that a professional, relationship-driven approach could help address this gap.
Rather than attempting to serve everyone immediately, they chose to begin with people they already knew through Sahib's professional network.
This gave the business a starting point based on existing relationships rather than requiring the founders to build an entirely new customer base from scratch.
The approach also provided an opportunity to understand what prospective investors needed, which questions they asked and what would make them comfortable considering unfamiliar investment options.
2. Building the Business on Existing Relationships
One of the earliest strategic decisions was to begin with Sahib's existing clients, many of whom were high-net-worth individuals who already used his accounting services.
Some clients were familiar with conventional financial instruments but had limited exposure to other investment opportunities. The founders saw an opportunity to help these clients consider mutual funds as part of a broader financial approach.
This was a practical way to establish the business.
The founders already had relationships with people who knew their professional background. They could begin conversations from a position of familiarity rather than relying entirely on cold outreach.
Over time, the business benefited from referrals from existing clients.
The experience reinforced a central lesson of financial distribution: people often need to trust the person explaining an investment before they feel comfortable considering the product itself.
Trust, therefore, was not simply a marketing advantage. It was fundamental to the business model.
For a mutual fund distributor, relationships can extend over many years, covering changing income levels, family responsibilities, retirement planning and evolving financial goals. Maintaining those relationships requires consistency, communication and a genuine understanding of each investor's circumstances.
Funds Ve'daa's early approach placed these relationships at the centre of its development.
3. Shifali Satsangee's Journey Into Financial Services
Shifali Satsangee brought an academic background in economics and marketing to the business. She is an economics graduate and holds an MBA specialising in marketing.
Her background offered a combination of financial understanding and commercial perspective.
Economics provided a foundation for understanding how people make decisions about money and resources. Marketing offered a different but equally important perspective: how to communicate value, understand customer needs and build lasting relationships.
As she became increasingly involved in mutual fund distribution, Shifali developed her professional credentials in the field. She obtained AMFI certification in 2011, according to a Moneycontrol profile published in December 2020.
She subsequently took a leading role in developing Funds Ve'daa as her own venture, with a team and a branch office in Delhi.
This stage marked an important development in her professional journey. She was not simply participating in a financial services business; she was building a professional identity in an industry where expertise, credibility and client confidence mattered enormously.
Her experience also reflected a wider opportunity for women in financial services entrepreneurship: developing specialised knowledge, building professional relationships and establishing credibility through consistent service.
4. Building Credibility in a Relationship-Driven Industry
Entering mutual fund distribution meant working in a business where customers had to make decisions about their savings and financial futures.
For investors unfamiliar with market-linked products, understanding the terminology, risks and possible outcomes could be challenging.
Shifali recognised that winning clients required more than presenting investment options. It required explaining the reasoning behind those options and understanding what each client was trying to achieve.
In an interview published by CafeMutual in 2011, she discussed the challenges she encountered as a woman independent financial adviser. She described situations in which prospective clients questioned women's competence in financial matters.
Her response was to emphasise research, detailed investor profiling and a structured approach to investment allocation.
Rather than relying on persuasion alone, the business needed to demonstrate professional preparation and a clear understanding of client requirements.
This approach is particularly relevant in financial services, where credibility develops through repeated interactions. A client may initially approach a distributor with questions about one investment, but a lasting relationship depends on how effectively the distributor communicates, responds to concerns and maintains service over time.
Shifali's experience highlights the importance of professional knowledge in overcoming initial doubts and building confidence.
5. Creating a Distinctive Business Model
Funds Ve'daa's development was supported by a decision to offer value beyond simply distributing mutual funds.
In its early years, the business drew on the founders' accounting and financial services background. The original approach included related services such as taxation and accounting alongside investment-related offerings.
This helped differentiate the business from a distributor whose relationship with a client might begin and end with a product transaction.
The broader approach gave clients an opportunity to discuss connected financial matters within a familiar professional relationship.
As the business developed, Funds Ve'daa placed increasing emphasis on mutual fund distribution, investment research, investor profiling and understanding clients' financial goals.
The underlying idea was straightforward: investment decisions should be considered in the context of a person's broader financial circumstances.
A suitable investment approach for one household may not be appropriate for another. Investors differ in their income, responsibilities, time horizons, liquidity requirements and ability to tolerate market fluctuations.
Understanding these differences is an important part of responsible distribution.
The business's focus on client requirements helped shape its identity around service and relationships rather than product sales alone.
6. Taking Financial Education Beyond the Office
A major challenge in expanding mutual fund distribution beyond India's largest cities is that access to investment products does not automatically create investment understanding.
People may have savings but lack the information required to compare financial options, assess risks or connect investment choices with long-term objectives.
Shifali addressed this challenge through financial awareness and educational initiatives.
According to Moneycontrol's December 2020 profile, she organised financial wellness programmes at universities, factories, Rotary clubs, professional organisations, the Agra Police Training Academy and the Income Tax Department.
These initiatives helped take financial conversations into workplaces and community settings where people might not otherwise seek investment guidance.
One example highlighted in the profile was an educational session for approximately 250 women police officers at the Bihar Military Police Training Centre in Patna. Following the programme, Shifali created an interactive WhatsApp group to provide further investing guidance.
This approach illustrates how financial education can extend beyond a one-time presentation.
A session can introduce concepts, but participants may need additional opportunities to ask questions, clarify terminology and understand how financial decisions relate to their own circumstances.
Continuing communication can help bridge that gap.
For a distribution business, educational programmes can also introduce the organisation to new communities and prospective clients. However, their broader value lies in making financial concepts more accessible and encouraging people to ask informed questions about their savings.
7. Expanding Beyond High-Net-Worth Investors
Funds Ve'daa initially concentrated on high-net-worth individuals within the founders' existing professional network.
As the business developed, its ambitions extended beyond this initial segment.
Shifali's work came to include both affluent investors and emerging-income families, according to published reporting.
Serving these different groups requires an understanding that investors do not all approach money in the same way.
Some clients may have substantial assets and complex financial requirements. Others may be starting systematic investment plans, building an emergency reserve or trying to understand how market-linked investments differ from traditional savings.
A distributor needs to adapt the conversation to the individual rather than assume that every client has the same level of financial knowledge or the same objectives.
For emerging investors, explaining the basics can be particularly important. They may need to understand market volatility, the importance of investment time horizons, the difference between saving and investing, and why returns cannot be guaranteed.
For more experienced investors, discussions may involve portfolio allocation, diversification and reviewing whether their investments remain aligned with their goals.
The ability to work with different client groups allowed Funds Ve'daa to pursue a broader role in financial distribution while retaining its focus on professional relationships.
8. Building Processes for Consistent Client Service
As a financial distribution business grows, maintaining personal relationships becomes more complicated.
More clients mean more questions, portfolio updates, transaction-related requests and follow-ups. If every task depends on the founder personally remembering what needs to happen next, service can become difficult to sustain.
Funds Ve'daa's approach included an emphasis on processes and ongoing client communication.
A Moneycontrol profile published in 2020 reported that the firm conducted investor risk profiling and sent monthly portfolio valuation reports to clients.
Risk profiling helps establish a clearer understanding of an investor's circumstances, financial objectives and willingness or ability to accept investment risk. Regular portfolio reporting can help investors review their holdings and remain informed about changes in value.
These practices also create a more structured relationship between a distributor and a client.
Instead of communicating only when a transaction takes place, the business can establish recurring touchpoints that support ongoing engagement.
For financial services entrepreneurs, this is an important operational lesson. A business becomes more sustainable when essential tasks are supported by repeatable processes rather than relying entirely on individual effort.
The challenge is to develop systems that improve reliability without making the client experience impersonal.
9. Embracing Technology and Professional Development
Financial distribution has evolved significantly as digital tools have become more accessible.
Client communication, documentation, transaction support and back-office administration can all place demands on a distributor's time.
Technology can help reduce repetitive work and make it easier to manage client information and routine processes.
In a 2021 interview with CafeMutual, Shifali discussed the growing interest in millennial investors and the firm's efforts to adopt technological upgrades to become more reliably phygital—combining physical relationships with digital services.
This direction reflects a broader change in how investors expect to interact with financial service providers.
Some clients prefer face-to-face discussions, especially when making important financial decisions. Others value digital communication, convenient access to information and the ability to manage routine matters without visiting an office.
A combination of personal interaction and technology can help serve these different preferences.
Professional development also remains important. Shifali has been featured in industry publications and has participated in discussions about financial distribution and business development.
Continuing to learn, exchange ideas with peers and understand changes in the industry can help distributors refine their business practices as investor expectations evolve.
For a founder, the lesson is that establishing a business is only the beginning. Maintaining relevance requires adapting the way the business operates.
10. Learning to Build a Business That Does Not Depend on One Person
One of the most important challenges for an independent financial distributor is moving from a founder-led practice to an organisation supported by systems and a capable team.
In a CafeMutual article published in 2026, Shifali reflected on advice she received from a client who operated a manufacturing business. The conversation concerned the demands of personally handling routine requests, reminders and other client-service tasks.
The lesson was that a business cannot rely indefinitely on the founder's individual energy. It needs processes that allow work to be handled consistently and efficiently.
This is a particularly valuable insight for entrepreneurs in professional services.
In the early stages, a founder may personally manage most client interactions, administrative tasks and business development. This can help establish standards and build close relationships.
As the business expands, however, the same approach can create a bottleneck. Every routine request competes with time needed for client meetings, strategic decisions and future growth.
Documented workflows, clear responsibilities and appropriate technology can help address this challenge.
The objective is not to remove the founder from the business. It is to allow the founder to concentrate on the work where professional judgement and personal relationships matter most.
For Funds Ve'daa, the continued emphasis on process and technology reflects the broader challenge of building a distribution business that can deliver consistent service as its client base develops.
11. What Other Entrepreneurs Can Learn From Shifali Satsangee
Shifali's journey offers several practical lessons for people building businesses in financial services and beyond.
Start With a Real Market Need
Funds Ve'daa emerged from an identified gap in professional investment services in and around Agra.
The founders did not need to invent an entirely new financial product. They recognised that investors could benefit from greater access to professional distribution and financial guidance.
Entrepreneurs can often find opportunities by identifying where existing solutions are difficult to access, poorly understood or inadequately supported.
Use Existing Relationships as a Starting Point
The business began by serving clients already connected to Sahib's professional practice.
This provided a practical starting point for understanding customer needs and establishing credibility.
Existing relationships cannot replace the need to deliver value, but they can help a new business begin with a foundation of familiarity and trust.
Build Credibility Through Expertise
In financial services, credibility is earned through preparation, clear communication and consistent conduct.
Shifali's emphasis on research and investor profiling illustrates why professional knowledge is essential when clients are making decisions about their money.
Educate Customers Instead of Simply Selling to Them
Financial awareness programmes helped Funds Ve'daa reach audiences beyond its existing client base.
Education can help people understand their options and ask better questions. It can also build longer-term relationships based on informed decision-making rather than short-term persuasion.
Develop Processes Before Growth Becomes Difficult
As the number of clients increases, recurring administrative work can consume time that would otherwise be spent improving service and developing the business.
Structured workflows and appropriate technology can help a firm manage complexity without sacrificing the quality of its relationships.
Adapt to Changing Customer Expectations
The combination of personal interaction and digital service reflects the changing expectations of investors.
Businesses that remain attentive to these changes are better positioned to refine their service model as their customers' needs evolve.
Think in Terms of Long-Term Relationships
Financial distribution is not simply about completing transactions. Investors' needs change over time, and ongoing communication can help ensure that their financial decisions remain connected to their goals.
A relationship built on trust, professionalism and continuity can be more valuable than a single successful sale.
The Bigger Picture
Shifali Satsangee's journey with Funds Ve'daa illustrates how a financial services business can develop by addressing a local need with a professional, relationship-driven approach.
Beginning in 2002, the business grew out of the founders' recognition that investors in and around Agra could benefit from greater access to mutual fund distribution and related financial services.
Shifali's subsequent leadership brought together her economics and marketing background, professional development in mutual fund distribution, emphasis on investor education and focus on client service.
The business's approach evolved through financial awareness programmes, a wider client base, recurring portfolio communication and the adoption of technology.
Its story also highlights the challenges faced by entrepreneurs in professional services: establishing credibility, explaining unfamiliar products, managing growing workloads and developing processes that support consistent service.
The broader lesson is that a financial distribution business is built on more than investment products. It depends on understanding customers, communicating clearly, managing relationships responsibly and creating an operating model that can serve people over time.
For aspiring mutual fund distributors, independent financial advisers and other service-based entrepreneurs, Shifali's experience offers a useful example of how local relationships and professional knowledge can become the foundation of a lasting business.
A successful distribution business does not simply connect people with products. At its best, it helps people understand their choices and make decisions with greater confidence.